
Dome Option Fund 1 · Ashkelon, Israel
Five thousand homes.
One fixed price.
A right to 5,000 new homes in Ashkelon at ₪23,000/m², fixed until delivery in 2035–36. Paid in stages, secured as loans, and offered only to accredited investors.
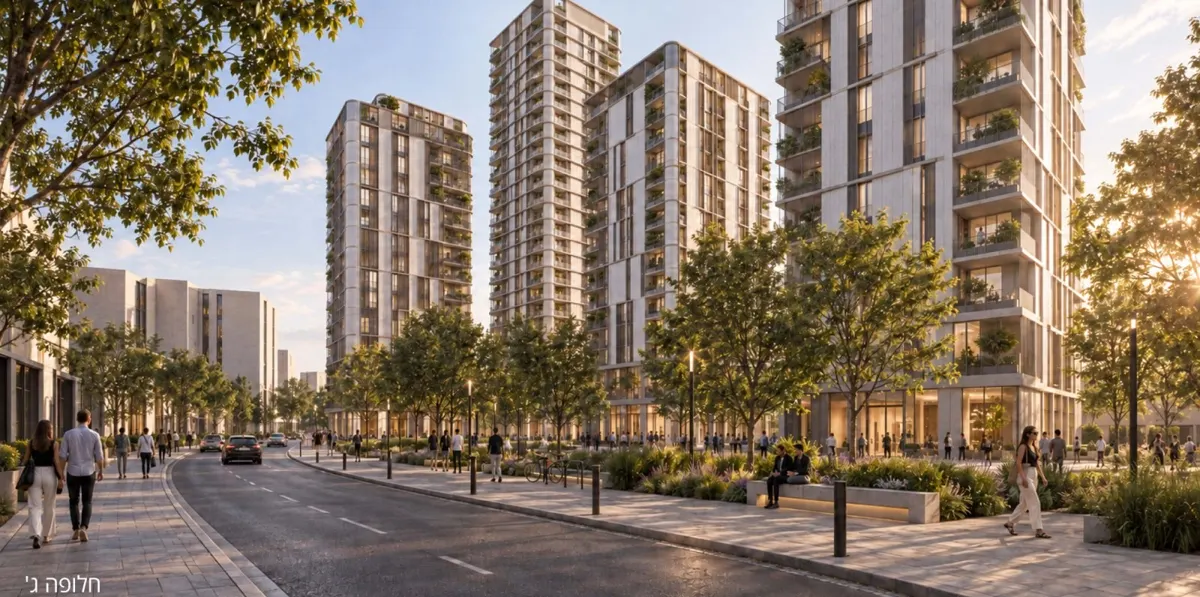
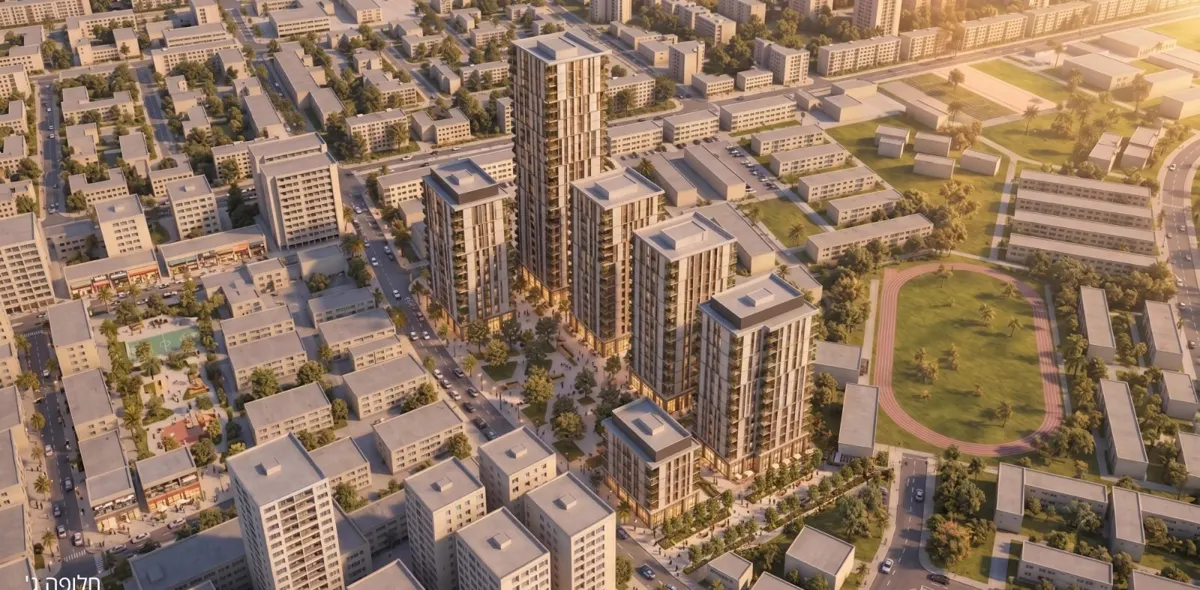
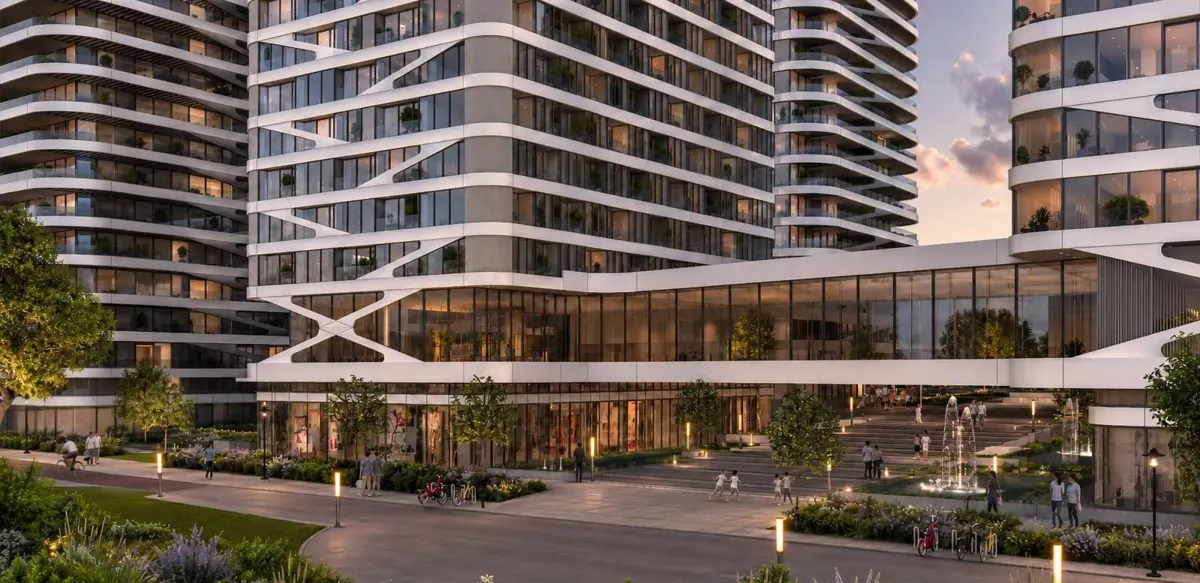
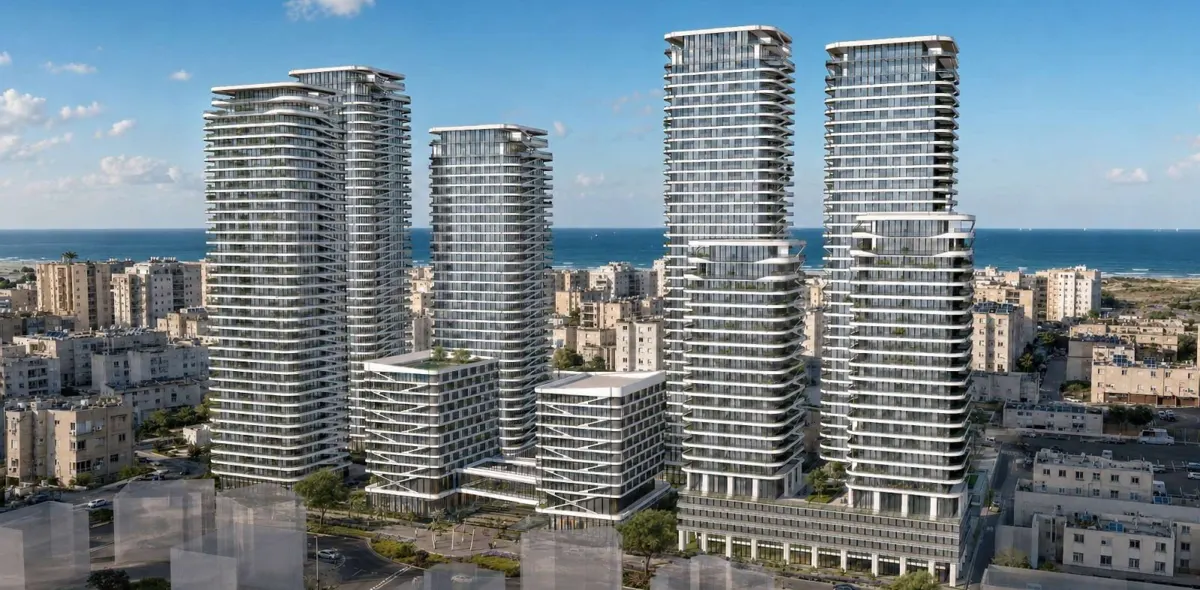
Renders: LSA Architects for Kidmat Hitchadshut.
The bigger picture
Under one Dome
Shimshon is being rebuilt, compound by compound. Old four-storey blocks become towers, parks and streets, and Dome's idea is that a new neighbourhood should work from the first day: energy, mobility, care and community, run by one operator for every building.
That is the story. The investment is narrower and simpler: a fixed-price right to 5,000 of the new homes. The neighbourhood services come with the homes as an amenity, provided by Dome's separate operating company. The fund does not pay for them or own them, and the numbers below assume no price premium from them.
Illustrations of the neighbourhood vision, not plans or renders of the compounds.
The investment
A priced call on 5,000 homes, paid in stages and secured as loans
| Item | In short |
|---|---|
| Asset | Right to 5,000 new homes (500,000 m²) in seven Kidmat compounds in Shimshon, Ashkelon |
| Price | ₪23,000/m² to the investor, fixed until delivery. Kidmat's price is ₪22,000/m². |
| Payments | 5% in 2026–27, 20% at the permit (~2031), 75% at delivery (2035–36), mostly from end buyers |
| Structure | Secured loans plus a right of first refusal now; a Section 49J unique option in the last 24 months |
| Base case | ₪28K/m² in 2035: 1.79× at year 2, 2.32× at the permit, 1.40× and 6.5% a year held to delivery |
| Downside | Below ₪25.6K/m² the investor does not exercise and the loans are repaid |
| Conditions | A signed agreement with Kidmat and the tax ruling before any capital is called |
The opportunity
Lock a 2035 home at a price that needs only 4–5% a year to work
| Benchmark (Oct 2026) | ₪ per m² | Note |
|---|---|---|
| Citywide average, second-hand | ~15,000 | Build's 2026 figure |
| Ir HaYayin median (newest district) | 16,800–17,310 | Down about 10% in a year |
| Ashdod average | 19,000–20,000 | Ashkelon is about 23% cheaper |
| Investor price, fixed | 23,000 | Until delivery, 2035–36 |
| Investor breakeven in 2035 | 25,608 | Price + 8% purchase tax + 3% selling cost |
From ~₪17.3K today to ₪25.6K in 2035 is about 4.6% a year. Ashkelon did 5.7% a year from 2010 to 2025.
Prices are soft today. That is the point of buying now, but the base case does not assume a recovery beyond the city's own long-run pace.
Residential construction starts in Ashkelon (CBS, via Build). Starts fell 83% from 2021 to 705 in 2025, so homes not started now are missing in 2028–30.
TERA PARK: 370,000 m² of hi-tech and offices in the first plan, about 1,000 jobs in phase one. The city absorbs 500–1,000 renewal homes a year, which shapes the exit plan.
The developer and the compounds
Seven compounds, all the signatures in hand
| Compound | Homes today | Homes after | Architect |
|---|---|---|---|
| HaEin / Kidmat HaYam | 1,189 | 8,323 | Miloslavsky |
| Ephraim Tzur | 487 | 3,409 | Miloslavsky |
| Ben Azai | 232 | 1,624 | LSA |
| David Raziel | 186 | 1,581 | Kaiser |
| Yulish | 211 | 1,477 | Primovitz Bass |
| Kalanit (Yoseftal) | 152 | 1,064 | LSA |
| Spinoza | 84 | 714 | Kaiser |
| Total | 2,541 | 18,192 |
- Kidmat Hitchadshut plans about 42% of Shimshon's existing homes.
- Plans are scheduled for deposit by Oct 2027 and approval by end 2028.
- Kidmat keeps land, planning, construction and residents. The investor takes none of those risks; the risk is the 2035 price and Kidmat's delivery.
- Kidmat is controlled by Eli Schlossberg, the sponsor's brother. See governance below.
Structure
One American company, one Israeli company, one developer
- InvestorsSubscribe for units in Dome Option Fund 1, a Delaware company. US investors must be accredited and verified (Reg D 506(c)).
- Dome Option Fund 1 (US)The sole investor in the Israeli company. It holds nothing else.
- Israeli companyWholly owned by the US company. Lends to Kidmat against security and holds the right of first refusal and, later, the option.
- Kidmat HitchadshutBorrows the 5% and 20%, grants a right of first refusal on 5,000 homes, and a Section 49J unique option in the last 24 months.
Why loans first
The building permit is about 50 months away. A Section 49J unique option can last only 24 months, so a long option could be taxed as a sale at signing. The loans are real: interest, security and a repayment schedule, with no duty to exercise and no penalty for walking away.
The tax structure is still an alternative that needs further clarification with tax counsel and an advance ruling from the Israel Tax Authority. The commercial terms are designed to hold under any structure the advisers choose.
Terms
What the investor pays, and when
| Payment | When | Per m² | On 500,000 m² | US$ at ₪3.09 |
|---|---|---|---|---|
| 5% (Tier 1: 500 homes; Tier 2: 4,500 homes in six tranches) | 15 Nov 2026 – Nov 2027 | ₪1,150 | ₪575M | $186M |
| 20% at the building permit | ~Jan 2031 | ₪4,600 | ₪2.30B | $744M |
| 75% at delivery | 2035–36 | ₪17,250 | ₪8.62B | $2,791M |
| Total | ₪23,000 | ₪11.5B | $3,722M |
Two raises, years apart. The 5% (₪575M) is raised now and paid in stages. The 20% (about $744M) comes around 2031 from the same or new investors, or mezzanine and bank debt. If it is not raised, the fund can sell part of its position at the permit.
Sponsor spread. Kidmat's price is ₪22,000/m². Dome keeps ₪1,000/m², ₪500M in total, earned in step with the investor's payments (₪25M, ₪100M, ₪375M). The ₪375M is earned only if the homes are bought at delivery.
Still to be set. Management fee, carried interest, sponsor co-investment, minimum ticket and loan interest from Kidmat will be set in the fund documents. All returns here are before them.
Returns
Four price cases for 2035, and what each pays the investor
| 2035 price per m² | Margin per m² | Year 2 | Permit (year 4) | Hold to delivery | IRR |
|---|---|---|---|---|---|
| Stress: ₪20K | ₪0 | 1.00× | 1.00× | 1.00× (walk away) | — |
| Bear: ₪24K | ₪0 | 1.00× | 1.00× | 1.00× (walk away) | — |
| Base: ₪28K | ₪2,320 | 1.79× | 2.32× | 1.40× | 6.5% |
| Bull: ₪34K | ₪8,140 | 3.79× | 5.62× | 2.42× | 17.2% |
An honest reading. Held to delivery, the base case is modest: 1.40× and 6.5% a year. The strongest value per shekel is the 5% position at the permit. The upside sits in the bull case.
Base ₪28K is Ashkelon repeating its 15-year pace; bull ₪34K assumes the city closes part of its gap to Ashdod. Margin per m² = 97% of the 2035 price − ₪23,000 × 1.08. Values before loan interest, fund fees and taxes. Early exits need a buyer at that price; liquidity is not guaranteed. A stronger shekel raises the dollar return and a weaker one lowers it.
Protection and risks
Capital moves only at milestones, and each one is a decision point
| Checkpoint | If good | If bad | Investor money at risk |
|---|---|---|---|
| Now → Nov 2027 | Fund the 5% as a secured loan + right of first refusal | Do not fund later tranches | Tranches paid so far |
| Plans approved (end 2028) | Prepare the 20% | Stop; the loan is repayable | ₪575M, secured |
| Permit (~2031) | Lend the 20%, or sell the position | Do not lend; demand repayment | Up to ₪2.88B, secured |
| Last 24 months | Take the unique option; sell or assign | Do not exercise; loans repaid | — |
The protection is only as good as Kidmat's credit and the security. If Kidmat cannot repay, the investor's 5% and 20% are at risk. Credit diligence on Kidmat is a condition of the raise. Security to be negotiated: charges on Kidmat's rights in the compounds, a parent guarantee, assignment of sales proceeds, and Dome as loss payee on the contractor's insurance.
Governance
Brothers on both sides of the deal. Everything is disclosed and checked.
- Related parties. Ben Schlossberg (sponsor) and Eli Schlossberg (Kidmat) are brothers. The deal is between Dome and Kidmat, with an independent appraisal and board approval on both sides.
- The guardrail. No investor money before a signed agreement with Kidmat and the tax ruling.
- Ring-fencing. The Israeli company holds only the Ashkelon loans and rights. Dome's neighbourhood-services business is separate and outside the fund.
- Reporting and rights. Quarterly reporting on planning, permit, construction and price evidence. Advisory committee approval for any change to price, security or Kidmat's terms.
The sponsor
Ben Schlossberg, Dome Communities
I spent almost twenty years in real estate abroad. I acquired and integrated more than ten million square feet of property, and I have built, and am building today, more than 1,000 homes.
Today I invest only in Israel. I learned that without a strong developer, urban renewal stalls on signatures, permits and finance. Dome does the opposite: it enters at a fixed price next to a developer who already carries those risks, and leaves land, planning and construction with him.
Tax ruling: Nimrod Yaron. Market study: Build. Architects: Kaiser, LSA, Miloslavsky, Primovitz Bass. Fund counsel, administrator and auditor to be appointed.
Timeline
From signature to keys
- Nov–Dec 2026Signed agreement with Kidmat; tax ruling filed. Tier 1 target: 15 Nov 2026.Commitments; no money before signing
- Jan–Nov 2027Tier 2 in six tranchesFund the 5% in stages
- Oct 2027Plans deposited—
- End 2028Plans approvedFirst exit window
- ~Jan 2031Building permitFund the 20%, or sell the position
- ~2033–34Last 24 months: Section 49J unique optionSales and assignments begin
- 2035–36DeliveryExercise, sell, assign or hold
How to invest
Five steps, and no money until the deal is signed
- Request the memorandumFill in the short form below. We send the 20-page memorandum and arrange a call with the sponsor.
- Data roomTerm sheet, tax memo, Kidmat's plans and signing status, the market study and the financial model.
- VerificationUS investors are verified as accredited (Rule 506(c)). Non-US investors confirm their local eligibility; in Israel, qualified investors only.
- Subscription agreementInvestors sign a subscription agreement with Dome Option Fund 1, the US company that is the sole investor in the Israeli company.
- Capital in stagesNo money is accepted before a signed agreement with Kidmat and the tax ruling. After that, capital is called in stages with the 5% payments.